Data Center Infrastructure Growth: Florida Statewide Market Outlook
9/8/2026 - By Stephen Reyes
Why Florida Matters Now
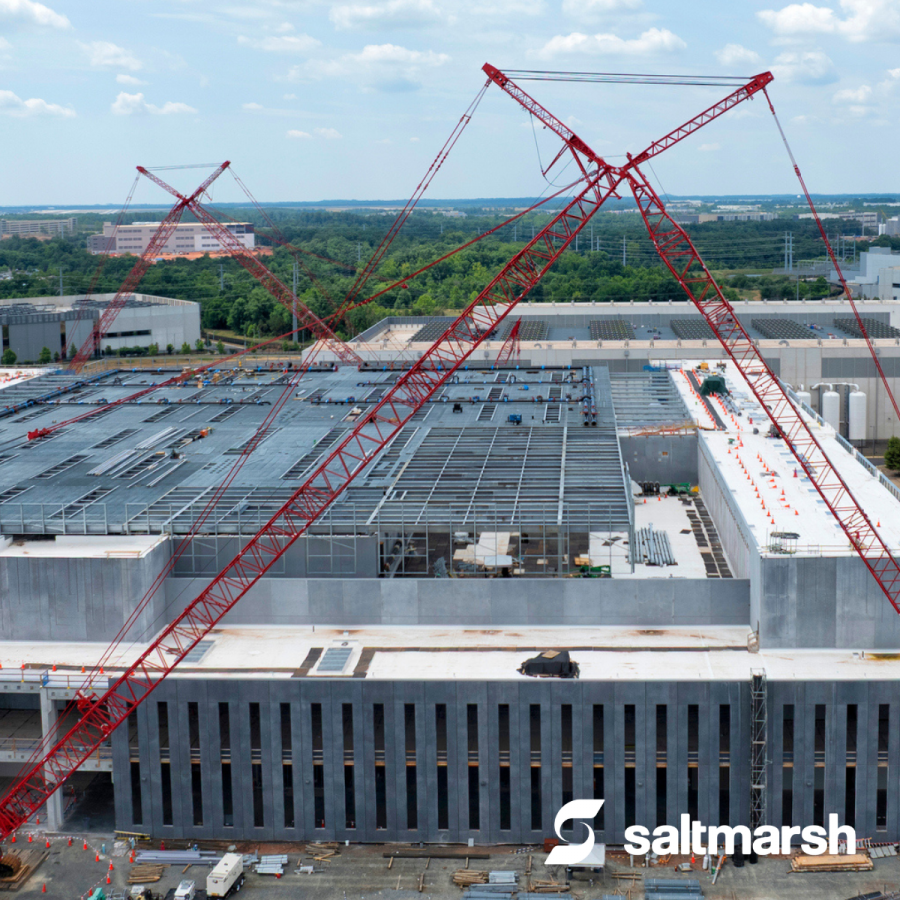
Across the United States, data center construction has become one of the fastest-growing segments in the built environment. Demand has been driven by artificial intelligence, cloud computing, and digital transformation, while available capacity in traditional hubs remains constrained. As development pressure increases in those established markets, project activity is expanding into secondary and emerging markets where power access, land availability, permitting conditions, and geographic resiliency may be more favorable.
Florida is increasingly part of that conversation. The state has historically lagged behind traditional hyperscale hubs, in part because of hurricane exposure and its potential to disrupt the electric grid. But over the past year, Florida has recorded its first approved hyperscale data center project, continued colocation and edge activity in South Florida and Tampa Bay, new developer interest along the Gulf Coast, and a sweeping new state law that will shape how future projects are sited, permitted, and financed. For construction companies anywhere in the state, this is no longer a single-market story. It is a statewide trend with distinct opportunities emerging in nearly every region.
Where the Growth Is Happening Across the State
Data center activity in Florida is not concentrated in one place, and the type of opportunity varies meaningfully by region.
- Central Florida (Polk County): Home to Florida's first approved hyperscale data center, a roughly $2.6 billion, 1,000-plus acre project in Fort Meade. Projects at this scale involve extensive site work, power infrastructure, and large multi-trade subcontractor teams.
- South Florida (Miami-Dade): An established and growing colocation market, including Iron Mountain's 150,000-square-foot, 16-megawatt MIA-1 facility, expected to begin operating in 2026, alongside continued interest from other colocation and edge providers and smaller proposed projects such as a micro data center planned for Homestead.
- Tampa Bay: An active edge and colocation market with a long-established data center and interconnection presence, now seeing renewed developer interest, including a proposed small-scale Edge facility in Pinellas Park.
- Gulf Coast and the Panhandle (Pensacola/Escambia County): An emerging market where local economic development officials have confirmed active negotiations with a data center developer, following inquiries from several other companies, positioning the region as a newer entrant to the state's data center landscape.
- North Florida (Jacksonville/Duval County) and other secondary markets: Smaller existing facilities and continued long-haul fiber and connectivity infrastructure that support the state's broader digital backbone.
For contractors, the throughline across every region is the same: national and regional developers and general contractors will be looking for local subcontractors who understand site conditions, can mobilize quickly, and can meet the documentation and reliability expectations of mission-critical construction.
A Broader Opportunity for Construction Companies
One of the most important points for small to midsized companies is that data center construction is not reserved only for the largest contractors. Major projects are commonly led by national general contractors, but those companies rely heavily on subcontractors across dozens of trade packages. Site prep, land clearing, underground utilities, concrete, steel, roofing, insulation, electrical, mechanical, HVAC, plumbing, controls, and specialty trades can all play a role, regardless of which part of the state a project is located in.
Mechanical and electrical systems often receive the most attention because power and cooling are central to data center performance. However, every phase of the project matters. Site readiness, stormwater management, envelope integrity, safety execution, quality documentation, and schedule reliability all affect the success of mission-critical construction. For Florida-based companies statewide, experience with humidity, storms, moisture control, wind resistance, and resilient building practices can also become an important differentiator, whether a project sits on the coast or further inland.
Recent Market Developments
Several developments over the past few months illustrate how quickly Florida's data center landscape is moving, and why the opportunity now touches nearly every region of the state.
Florida's First Hyperscale Project
In April 2026, Fort Meade city commissioners in Polk County unanimously approved a developer agreement for what is described as Florida's first hyperscale data center, a roughly $2.6 billion project planned on more than 1,000 acres (reported acreage has ranged from approximately 1,100 to 1,300 acres across coverage of the project) just west of U.S. 98. The project still requires additional permits before construction can begin, and it advanced despite sustained community opposition, with residents saying they felt misled and had expected more opportunity to weigh in before the agreement was finalized.
South Florida & Tampa Bay Activity
Miami-Dade continues to see steady investment, including Iron Mountain's MIA-1 facility, which has topped out and is expected to begin operating in 2026 on carbon-free energy, and a proposed small glass-enclosed micro data center, nicknamed the 'Fish Bowl,' planned for Homestead in South Miami-Dade. In the Tampa Bay area, American Tower has proposed a small-scale Edge data center in Pinellas Park, a project city officials describe as still in a pre-development, exploratory stage.
New Gulf Coast Interest
In Escambia County, Florida West Economic Development has confirmed it is in active negotiations with a data center company for a facility of roughly a couple hundred thousand square feet, following inquiries from five separate data center companies. The discussion has also generated a community petition and resident concerns about power, water, noise, and compatibility with nearby military installations, a preview of the kind of public engagement likely to accompany new projects statewide.
Senate Bill 484
Governor Ron DeSantis signed SB 484 into law on May 7, 2026, with its core provisions effective July 1, 2026. The law defines a 'large-scale data center' as a single location with an anticipated peak load of 50 megawatts or more. It bars utilities from shifting large-scale data center electricity costs onto residential and small business customers, confirms that local governments retain authority over comprehensive planning, zoning, and land development decisions affecting where these facilities can be built, and creates new consumptive-use water permitting requirements, including the potential use of reclaimed water, for qualifying projects. Utilities must file related tariffs with state regulators by October 1, 2026, and the law directs an independent study of the broader economic, resource, and public health impacts of large-scale data center development in Florida. Because SB 484 applies statewide, its zoning, ratepayer, and water permitting provisions are relevant to every region covered in this piece, not just the largest projects.
According to industry project tracking, Florida has roughly a dozen operating data centers and about eight additional planned projects, with planned capacity now measured in the thousands of megawatts, a marked increase from the state's historically modest data center footprint. Representatives of the data center industry have also said Florida is increasingly part of the national conversation about where the next wave of data center capacity will be built, even as hurricane exposure and grid resiliency continue to shape how and where projects move forward.
Positioning for Success Statewide
Because major data center projects are typically led by national or regional general contractors, Florida companies should focus on relationship building beyond their immediate local market. Contractors should identify general contractors and developers active across their region and the broader Southeast, then pursue prequalification, safety documentation, capability statements, and targeted outreach, well before a scope package is issued.
Reliability will matter as much as price. General contractors in mission-critical construction value subcontractors that can mobilize crews, protect schedules, coordinate effectively, and maintain documentation. A small or mid-sized contractor that consistently delivers can become highly valuable, even if its first role is a limited scope or supporting package rather than a major contract, regardless of which Florida market it operates in.
Workforce, Financial Readiness, and Internal Controls
Labor availability will be a central issue in every Florida market. The data center sector is already competing heavily for electricians, HVAC technicians, mechanical trades, and specialty workers. Companies statewide should evaluate whether they have the workforce strategy needed to support fast-moving projects, including apprenticeships, training partnerships, retention plans, and trusted labor relationships.
At Saltmarsh, we also encourage contractors to look at the business side of readiness. Strong job costing, cash flow management, bonding capacity, contract review, insurance coordination, and project controls can help companies participate in larger and more complex work without taking on unnecessary exposure. This is especially important when working under national general contractors with more sophisticated contract requirements, a pattern that holds true whether a project is in the Panhandle, Tampa Bay, Central Florida, or South Florida.
Community and Regulatory Factors
Community opposition to data centers, often referred to as NIMBY or Not In My Backyard concerns, has become a consistent theme across Florida's emerging projects. The Fort Meade approval in Polk County drew significant resident pushback despite passing unanimously, and the newer discussions in Escambia County have already generated a public petition. Concerns raised across these markets track closely with national patterns: power consumption, water usage, noise, land use compatibility, and environmental impact.
SB 484 now gives local governments statewide clearer statutory tools to weigh these concerns, and it adds a dedicated water permitting track for large-scale facilities. Contractors should expect increased attention to permitting, environmental controls, site buffering, and mitigation as a routine part of data center-related projects across the state, not an exception limited to any one market.
This can create additional scopes of work. Sound barriers, landscaping, stormwater improvements, environmental protection, erosion control, and utility upgrades may all become part of the broader construction opportunity. Companies with strong compliance discipline and local permitting awareness may be better positioned to support these needs, wherever in Florida they operate.
Key Takeaway for Florida Contractors
Florida's data center market has moved from a scattered set of individual projects to a genuine statewide trend, with Central Florida hosting the state's first hyperscale project, South Florida and Tampa Bay building on established colocation and edge markets, and the Gulf Coast emerging as a newer point of interest. A new statewide regulatory framework now shapes how every one of these projects gets sited, permitted, and financed.
For small to midsized construction companies anywhere in Florida, the practical path is the same regardless of region: become easier to trust, easier to qualify, and easier to work with on complex projects, and build relationships with the developers and general contractors active in your area before a scope package is issued. That is where the next wave of opportunity is likely to be won.
About the Author | Stephen Reyes, CISA, CISSP
Stephen is a partner who leads across information technology services, IT compliance, and security audits. He began his career in technology consulting over 30 years ago and joined the firm in 1997.He holds multiple professional certifications, including Certified Information Systems Auditor (CISA), and Microsoft Certified Systems Engineer (MCSE), along with credentials from ISACA, Novell, Citrix, and CompTIA. Stephen specializes in IT compliance and security audits, system selection, implementation, and conversion. His extensive expertise helps clients align their technology infrastructure with operational and regulatory demands.
Related Posts
- Data Center Infrastructure Growth: Tampa Market's Emerging Role
- Data Center Infrastructure Growth: Gulf Coast Market Outlook
- Data Center Infrastructure Growth: Florida Statewide Market Outlook
- IRS Ends First-Time Abate: What Construction Companies Need to Know
- Closing Time: What Contractors Need to Know About Month- and Year-End Close
- Expert Tips to Maximize Your Construction Job Schedule for Profitability
- Summer Outreach Heats Up
- Real Estate Accounting Services for Cash Flow Visibility and Portfolio Performance
- Cost Forecasting for Contractors
- Avoid Costly Bookkeeping Mistakes in Your Construction Projects
- How Does a Construction Bond Work?
- Construction Cost Accounting for Commercial Contractors
- Fueling Contractor Growth with Accounting Insights
- Margins & Mindset: A Contractor's Guide to Smarter Financial Growth
- Construction Accounting Methods Explained: Cash, Accrual, and Percentage-of-Completion
- Stop the Profit Leaks: 6 Gut checks for Contractors
- A Practical Guide to Construction Job Costing for Contractors
- WIP Construction Accounting: How to Read and Use a Work-in-Progress Report
- Saltmarsh Leader Suzanne Bach Joins ABC Florida Gulf Coast Board
- Job Schedules 101: A Smarter Way to Strengthen Construction Finances
- A Quick Guide to Percent of Completion for Long-Term Construction Contracts
- Four Metrics Your Construction Company Should Start Tracking Today
- WEBINAR: Horror Stories in Employee Safety/Risk Management
- White Paper: Manufacturing Outlook, Leveraging Technology Today
- Webinar Materials: The Cost of Attracting & Retaining Talent in Today's Market
- View All Articles